
Singapore is Southeast Asia's most digitally competitive economy, with 5.42 million digital payment users and transaction values exceeding $30.7 billion in 2025. Digital wallets overtook bank cards at the physical point of sale for the first time in 2025 — a structural shift extending to online checkout. The market holds the highest credit card penetration in Southeast Asia at 80%, making card-plus-wallet the defining payment combination for merchants entering this market.
Key figures: Singapore
Country | Singapore |
|---|---|
Population | 6.1 million |
GDP (USD) | $603.9 billion |
Currency | Singapore Dollar (SGD) |
Credit card penetration | 80% (highest in Southeast Asia; Statista) |
Digital payment adoption | ~89% (5.42 million users; Statista 2025) |
Which Payment Methods Do Singapore Buyers Use Most?
Digital wallets hold 40% of Singapore's e-commerce market, credit cards 34%, and bank transfers 11%. Together wallets and cards account for 74% of online transaction volume. Singapore's 2025 payment breakdown:
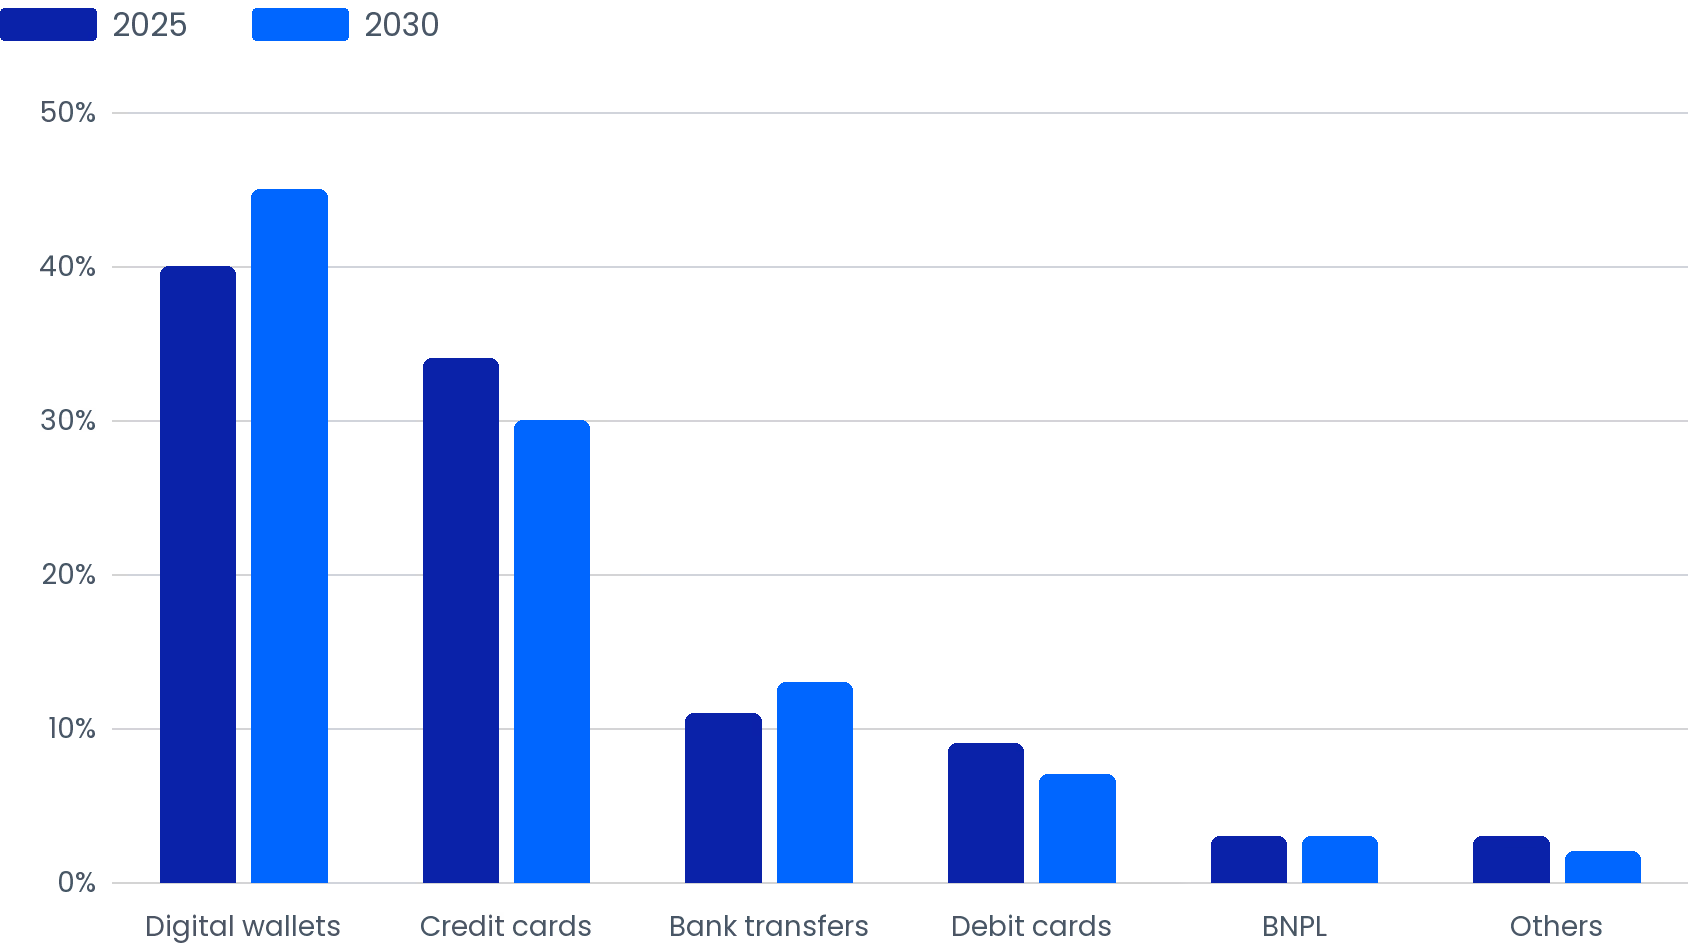
Digital wallets — 40%, growing to 45% by 2030. GrabPay and ShopeePay lead locally; PayPal and Apple Pay serve cross-border and premium shoppers. In 2025, wallets surpassed bank cards at the physical point of sale for the first time.
Credit cards — 34%, declining gradually to 30% by 2030. Singapore holds the highest credit card penetration in Southeast Asia at 80%. Consumers are increasingly binding cards inside digital wallets like Apple Pay — making direct card entry a background step at checkout.
Bank transfers — 11%, projected to reach 13% by 2030. Built on PayNow and the SGQR (Singapore Quick Response) unified QR standard. Real-time clearing with no chargeback exposure.
Debit cards — 9%, declining to 7% by 2030. As consumers migrate card credentials into wallets, standalone debit card use at checkout is declining.
BNPL — 3%, stable through 2030. Functions as an add-on that lifts average order value (AOV); not a primary acquisition channel in this mature market.
Singapore E-Commerce Payment Method Share (2025)
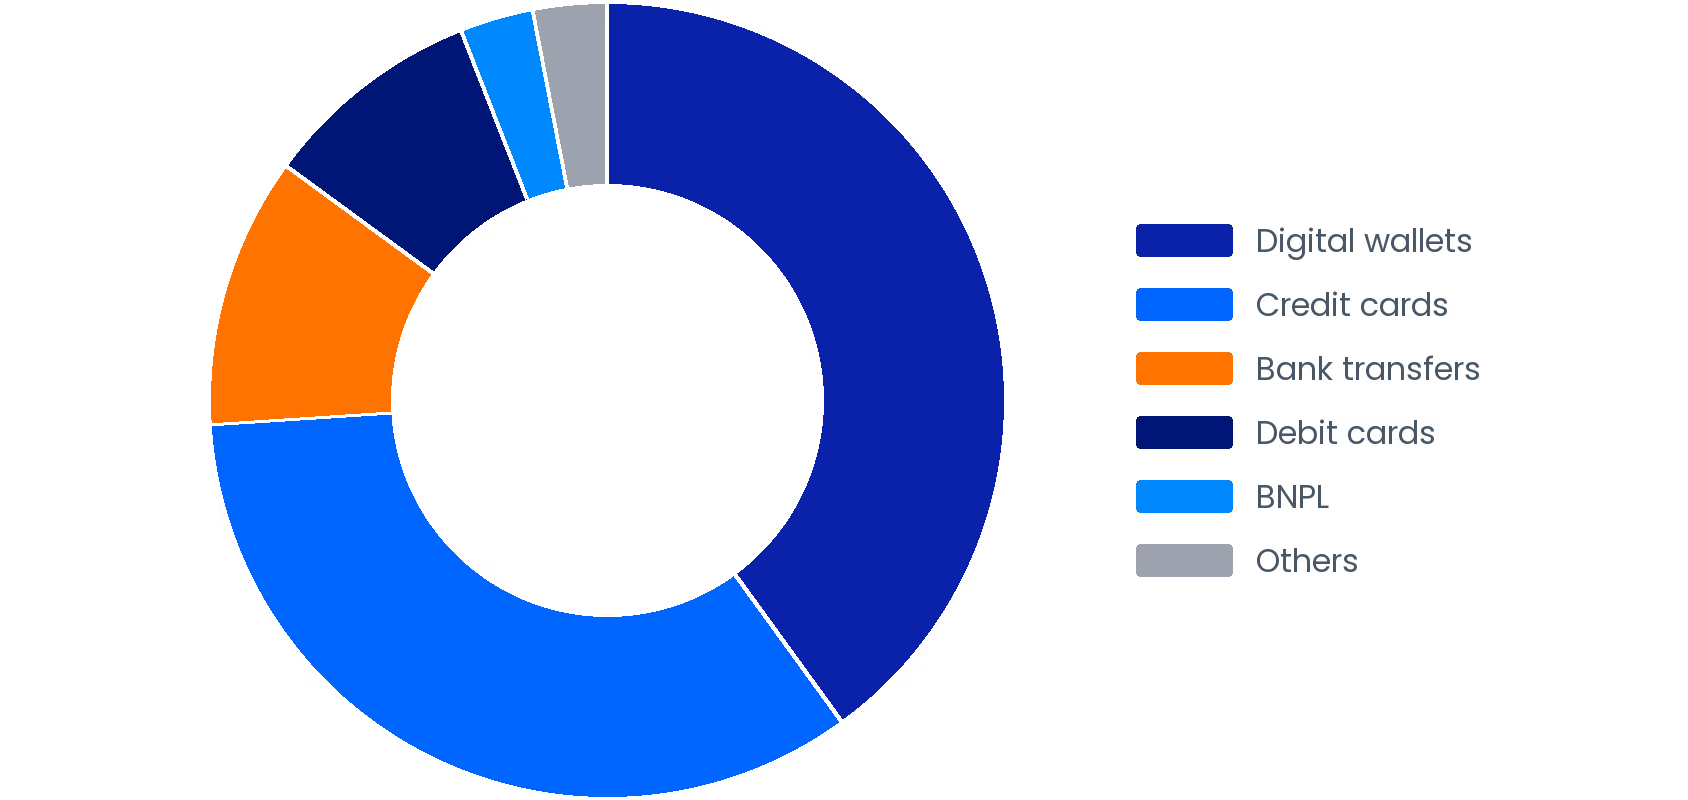
How Digital Wallets, Credit Cards, and PayNow Work for Merchants in Singapore
Singapore's payment methods differ primarily in integration requirements and fraud exposure: local wallets require separate merchant onboarding, cards need 3DS2 compliance, and PayNow delivers irrevocable real-time settlement. The table below details platforms and the operational considerations for each method.
GrabPay and ShopeePay require local merchant onboarding; PayPal can be enabled without a local entity — making it the faster launch path for new market entrants. PayNow settlements are real-time and irrevocable, eliminating a common fraud vector for digital goods merchants. For merchants also operating in higher-fraud markets, cross-border card decline management and chargeback controls remain relevant even when starting from Singapore's low-risk baseline.
Payment Method | Key Platforms | Approx. Share | What Merchants Should Know |
|---|---|---|---|
Digital Wallets | GrabPay, ShopeePay, PayPal, Apple Pay | ~40% | GrabPay and ShopeePay require local merchant onboarding; PayPal can be enabled without a Singapore entity, making it the faster path to launch. |
Credit Cards | Visa, Mastercard | ~34% | 3DS2 (3-D Secure 2) authentication is expected for cross-border card-not-present transactions; ensure your payment provider handles this automatically. |
Bank Transfers | PayNow, SGQR | ~11% | PayNow settlements are real-time and irrevocable — no buyer-initiated reversal, which eliminates a common fraud vector for digital goods merchants. |
Debit Cards | Visa Debit, Mastercard Debit | ~9% | Debit spend limits can be lower than credit lines; display a wallet option alongside debit to reduce failed transactions on high-AOV orders. |
BNPL | Atome, Grab PayLater | ~3% | Merchant receives full payment upfront; credit risk and collections are carried by the BNPL provider. |
Which Payment Methods Are Growing in Singapore?
Digital wallets are the standout growth category, rising from 40% to 45% by 2030 as card credentials increasingly migrate into Apple Pay, Google Pay, and local wallets. Card share compresses from 34% to 30% — not a decline in card usage, but migration of the underlying card into the wallet layer. Bank transfers grow from 11% to 13%. For configuring a checkout that reflects this layered wallet-plus-card reality, the payment method quadrant framework provides a placement model for markets with overlapping dominant methods.
Singapore Payment Method Share: 2025 vs 2030 Projection